Key Takeaways
- A low doc home loan lets a self-employed borrower prove income with other evidence, usually an accountant's declaration, recent BAS lodgements or business bank statements, in place of two full years of tax returns.
- Full doc loans need the complete set: tax returns, Notices of Assessment and financial statements. In return, far more lenders will consider the application.
- Low doc lending is offered by fewer lenders and normally comes with higher pricing and a lower maximum LVR.
- If your business is established and your financials are lodged and current, full doc is usually the place to start, but if the business is new, your income moves around from year to year or your last tax return does not show what the business is earning now, low doc may be the more realistic option.
For most business owners, the question of low doc vs full doc home loans for self employed borrowers is settled less by which product looks better on paper and more by what evidence of income you can actually put in front of a lender today, and whether that evidence tells the true story of your business. Dark Horse Financial Pty Ltd is a Credit Representative No. 465 325 of Buyers Choice Licencing Pty Ltd ACN 626 172 281 (Australian Credit Licence No. 509484), part of the Money Quest Group. We arrange finance through a large panel of bank, non-bank and private lenders.
In this guide we cover how each loan type works and the documents you will need to gather, then compare the two on lending limits and pricing so that you can work out which one fits your documentation and what you are trying to achieve.

What Is a Low Doc Home Loan for Self-Employed Borrowers?
A low doc (low documentation) home loan is designed for self-employed Australians who cannot yet provide, or whose records do not accurately reflect, the standard income documentation lenders ask for. Rather than relying on two years of personal and business tax returns, the lender verifies income through alternative evidence, which commonly includes an accountant’s letter or income declaration, recent Business Activity Statements (BAS) and business bank statements.
Low doc products are offered by a subset of lenders rather than the market as a whole, and they typically come with different pricing and lending limits to full doc loans because the lender is working from a narrower view of the borrower’s finances. The specific figures are set out in the comparison table further below.
In our experience, the borrowers who use low doc loans tend to fall into one of three groups:
- People who have recently become self-employed and have not yet lodged two full years of tax returns for the business
- Business owners with seasonal or project-based work, where income can rise or fall noticeably from one year to the next
- Borrowers whose latest tax return understates how the business is trading, which is common after a strong growth period or a year of heavy reinvestment
For these borrowers, a low doc loan can provide a workable path into property ownership at a point when a full doc application would not reflect the real strength of the business.
What Is a Full Doc Home Loan and How Does It Work for the Self-Employed?
A full doc (full documentation) home loan is the standard home loan offered by most banks and non-bank lenders. For a self-employed applicant, it requires complete financial verification, which typically means two years of personal and business tax returns, the matching Notices of Assessment from the ATO and full business financial statements.
This documentation gives the lender the clearest possible view of serviceability, meaning your income, your existing commitments and your capacity to meet repayments over the life of the loan. Because the lender can assess a fuller financial picture, full doc applications are considered by a much broader range of lenders than low doc applications, and that breadth of choice is one of the main reasons established business owners favour this path when their financials are in order.
That is also where panel breadth matters. Lending policy for self-employed income differs from one lender to the next, including how each lender treats add-backs, one-off expenses and year-on-year changes in profit. Dark Horse’s role is to match your documentation profile to the one lender on our panel whose policy fits your circumstances and who is actively writing that type of loan, rather than submitting your application to several lenders and hoping one approves it.
Low Doc vs Full Doc Home Loan Documentation Requirements
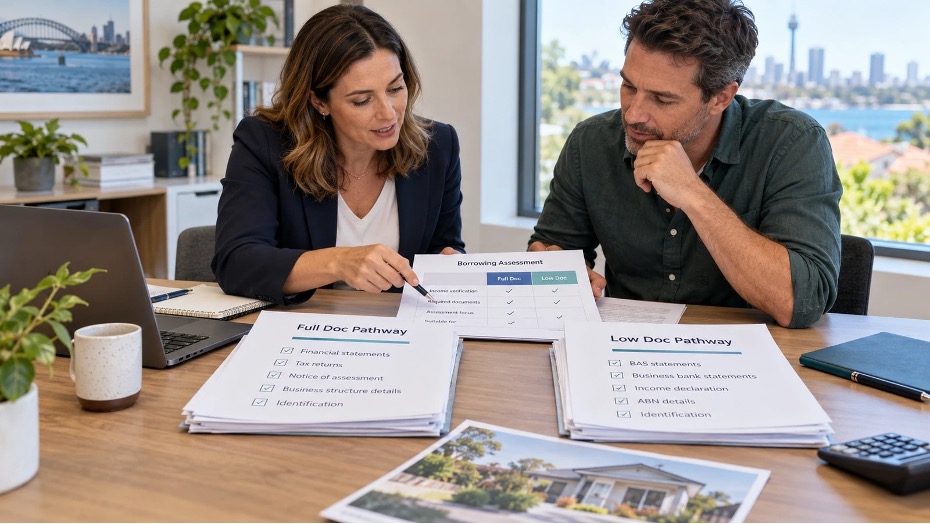
The most important difference between the two loan types is the evidence of income each one accepts, and that difference flows through to lending limits, pricing and the number of lenders available to you. The table below summarises how they compare.
| | Full Doc Home Loan | Low Doc Home Loan |
|---|---|---|
| Documentation required | Two years of personal and business tax returns, Notices of Assessment and full financial statements | Alternative evidence of income, typically an accountant’s letter or declaration, recent BAS and business bank statements (the accepted list varies by lender) |
| Typical LVR cap | Up to 90% to 95% with some lenders, generally with Lenders Mortgage Insurance (LMI) above 80% | Generally up to 80%, with some lenders setting a lower maximum |
| Typical rate premium vs full doc | Baseline (no premium) | Typically higher than full doc pricing; the margin varies by lender and product |
| Best suited for | Established self-employed borrowers with complete financials who want the widest lender choice | Recently self-employed borrowers, seasonal or variable incomes, or applicants whose latest tax return understates trading income |
Requirements can also differ between lenders that offer the same type of loan, so the checklists below are a guide to what you should expect to gather rather than a fixed list that applies to every application.
Full Doc Documentation Checklist
Most lenders assessing a full doc application from a self-employed borrower will want to see:
- Personal tax returns for the last two years
- Business tax returns for the same two years
- The matching ATO Notices of Assessment
- Business financial statements, meaning a profit and loss statement and a balance sheet
- Recent bank, savings and credit card statements
- Anything else the particular lender’s policy calls for, which can include an ATO portal statement or details of business debts
Low Doc Documentation Checklist
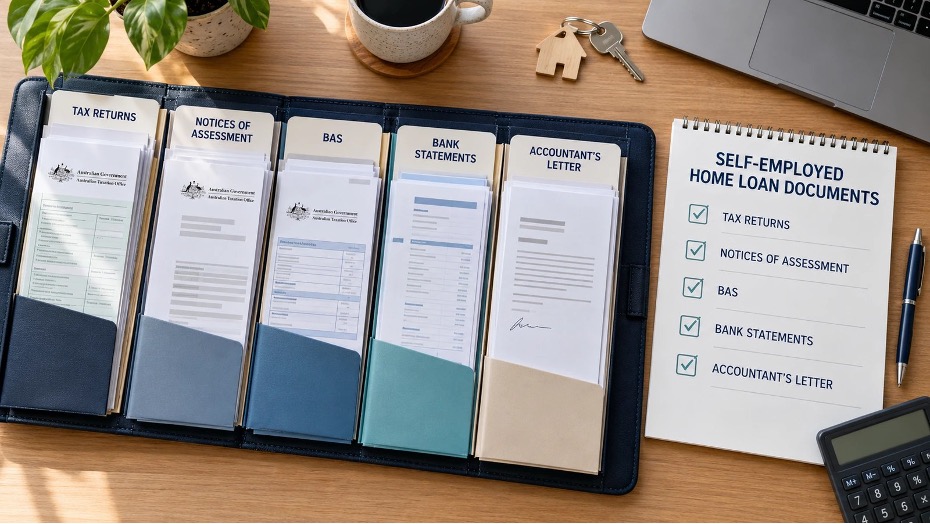
For a low doc home loan, the alternative evidence accepted will usually include some combination of:
- An accountant’s letter or income declaration
- Recent BAS lodgements, often covering the last two to four quarters
- Six to 12 months of business bank statements
- A signed income declaration from the borrower
- Evidence of an active ABN and GST registration for a minimum period set by the lender
It is worth noting that accountant’s letters have become harder to obtain, as many accountants are now reluctant to confirm a client’s income following guidance from their professional bodies and professional indemnity insurers, so lenders that accept BAS or bank statements in place of a letter can be especially useful. The exact list of accepted evidence varies by lender and changes over time.
Which Is Better for Self-Employed Borrowers: Low Doc or Full Doc?
Neither loan type is objectively better. The right choice depends on your documentation profile, how long your business has been operating and what you want the loan to achieve, both now and over the next few years.
A full doc loan is usually the stronger choice when:
- The business has been trading for at least two years
- Your tax returns and Notices of Assessment are lodged and current
- The income you have declared is a fair reflection of what the business earns
- Having the widest choice of lenders and loan features matters to you
A low doc loan is often more practical when:
- You have been self-employed for under two years
- Income is seasonal, or changes a good deal between financial years
- Your latest tax return does not show how the business is trading now
- You need to proceed with a purchase before your next financials are finished
For many borrowers the answer is not permanent either, because a low doc loan taken out while a business is young can often be refinanced to a full doc loan once two years of financials are available, which is covered in the FAQs below.
Because eligibility and pricing depend on which lenders are actively writing each product at the time you apply, and because each lender assesses self-employed income in its own way, the most reliable way to find out which option you qualify for is to have your situation assessed directly by a broker who works with self-employed borrowers every day. When you are ready to move from comparing loan types to finding the right lender, you can explore your home loan options with Dark Horse.
Pros and Cons of Low Doc and Full Doc Home Loans
Each loan type involves trade-offs, and understanding them before you apply makes it easier to choose the structure that suits your circumstances.
Pros and Cons of Low Doc Home Loans
The main appeal of a low doc loan is that it can open the door to finance earlier than a full doc loan would, although that flexibility does come at a cost.
Pros:
- Newly self-employed borrowers can reach finance sooner, without waiting for two years of lodged returns
- Two full years of tax returns are not needed
- It can work well where the latest return understates what you are earning now
- Seasonal and variable incomes are easier to accommodate
Cons:
- Fewer lenders offer it, so the choice is narrower
- Expect pricing to be higher than for a comparable full doc loan
- The maximum LVR is usually lower, which in practice means a bigger deposit
- What counts as acceptable evidence differs from lender to lender
Pros and Cons of Full Doc Home Loans
Full doc is the standard path, and for an established business with tidy financials it is generally the one that offers the most choice, but the documentation burden is real and the assessment is only as good as your most recent figures.
Pros:
- The widest range of lenders and loan products is available to you
- Serviceability is assessed in the most straightforward way
- Pricing is generally sharper than low doc
- Some lenders will go to higher LVRs
Cons:
- You need two years of complete tax returns and financial statements
- If the business has grown recently, older returns can understate what you can afford
- Lenders look closely at business performance, and a drop in profit will be questioned
- Pulling the full set of documents together can take a while
Tips for Self-Employed Home Loan Applicants
Preparation makes a measurable difference to how a self-employed application is assessed, whichever loan type you choose. These steps will put you in a stronger position before you apply.
- Keep your BAS and tax lodgements current. Overdue lodgements narrow your options under both loan types, and in a full doc application they can stop the process altogether until they are brought up to date.
- Keep personal and business banking separate. When the two are mixed it becomes much harder for a lender to see what the business is really earning, and this matters most where a low doc application is being assessed on bank statements.
- Work with your accountant on timing. If your next tax return will show a stronger result, it may be worth discussing whether to apply before or after it is lodged.
- Speak to a broker before choosing a loan type. Lending policy for self-employed income varies widely, and understanding how lenders assess self-employed income will help you see why one lender may view your application very differently to another.
- Gather your documentation early. Start collecting tax returns, Notices of Assessment, BAS and bank statements well ahead of applying so that a suitable property does not slip away while paperwork is outstanding.
- Declare your income accurately. Overstating income on a low doc declaration can lead to a loan you cannot comfortably repay, and lenders will check the declaration against your BAS and bank statements.
Conclusion and Next Steps
The choice between a low doc and a full doc home loan depends on how complete your financial documentation is and how established your business is. Full doc offers the widest lender choice when your financials are up to date and reflect your true income, while low doc provides a practical alternative for newer businesses, variable incomes and borrowers whose latest return does not show their current position.
Eligibility, lending limits and pricing all vary by lender, so the most useful next step is a conversation about your own circumstances. If you would like help working out which option suits your business and your property goals, get in touch with our team.
FAQs
The main difference is the type of income evidence the lender requires, not the purpose of the loan. A full doc loan is assessed on tax returns, Notices of Assessment and financial statements, while a low doc loan relies on alternative evidence such as an accountant’s letter, BAS and business bank statements.
Risk depends on the lender and on the borrower’s ability to service the loan, not on the documentation type itself. Lenders price low doc loans to reflect their narrower view of income, but for the borrower a low doc loan is only riskier if the income declared does not support the repayments.
Yes, this is generally possible by refinancing once you have two years of full financials available. Many self-employed borrowers use a low doc loan while their business is establishing and then refinance to a full doc loan, which can give them access to a wider range of lenders and loan features.
Pricing varies by lender and product, but low doc loans are typically priced higher than equivalent full doc loans because the lender is working with less financial information. Your LVR and credit history will also affect the rate offered.
The documents depend on the loan type, and the full doc and low doc checklists above set out what most lenders ask for. As a general guide, full doc requires tax returns, Notices of Assessment and financial statements, while low doc relies on BAS, bank statements and an accountant’s letter or income declaration.
Disclaimer: Loans and their accompanying benefits are available only to those who qualify for them and have been approved. Though we put a lot of care into writing this article, the information presented within is general and doesn’t consider your unique situation. It is not meant to serve as a substitute for professional advice, and you should not rely on it solely for any major financial decisions. You should always consult with a professional when you’re dealing with finance, tax, and accounting matters.
Choose Low Doc or Full Doc as a Self-Employed Borrower
The right application type depends on how up to date your tax returns are and how your income is structured. Send us an enquiry and we’ll compare self-employed home loans that suit your paperwork.