For Australian businesses carrying an overdue tax balance, the ATO General Interest Charge (GIC) is one of the most significant costs to understand and manage. The ATO GIC rates are reset every quarter, the charge compounds daily on unpaid amounts, and since 1 July 2025 it can no longer be claimed as a tax deduction. This guide sets out the current GIC rate, how the rate is set and calculated, how it differs from the Shortfall Interest Charge, and the options available to reduce or remove it, so it is worth checking the latest ATO GIC rates below before you decide how to deal with an outstanding tax debt.
Key Takeaways
- The GIC rate for the October to December 2026 quarter is 11.51% per annum, which works out to 0.03153425% per day.
- The ATO resets the rate every quarter using the 90-day Bank Bill rate plus 7 percentage points.
- Because GIC compounds daily it is charged on the unpaid tax and also on any GIC that has already been added.
- GIC and SIC stopped being tax deductible from 1 July 2025, so the business now carries the full cost.
- Remission is possible where the ATO accepts it is fair and reasonable, and you can still ask for it after the charge is paid.
From 1 July 2025: GIC Is No Longer Tax Deductible
GIC and the Shortfall Interest Charge (SIC) have not been tax deductible for Australian businesses or individuals since 1 July 2025. The change came in through the Treasury Laws Amendment (Tax Incentives and Integrity) Act 2025 and it covers charges incurred in any income year starting on or after 1 July 2025, and it makes no difference when the underlying debt first arose.
Previously, a business paying GIC above 10% could deduct that interest and reduce its effective cost. That deduction no longer exists, so the full GIC rate is now borne by the business and the real cost of carrying ATO debt has increased.
Interest on a commercial loan used for business purposes may still be deductible, so the comparison now favours refinancing more than it did before the change. The ATO’s guidance on interest charge deductibility sets out the rules, and we cover the topic in more detail in our article on ATO interest deductibility.
What Is the ATO General Interest Charge?
The ATO charges GIC on tax debts that remain unpaid after the due date. It is intended to encourage people to pay on time and to keep the system fair between those who pay on time and those who do not. The GIC is calculated on the part of the debt that has not yet been paid and grows every day, and it applies to most tax debts, including income tax, GST, PAYG withholding and other amounts owed to the ATO.
What Triggers GIC?
GIC is triggered by any overdue tax debt or liability. Specifically, it applies in the following situations:
- Failure to pay tax debts: Once the due date for payment passes, the ATO begins applying GIC to whatever remains outstanding.
- Incorrectly lodged tax returns: A late return, or one that misreports your tax obligations, can result in GIC on any unpaid amount that flows from it.
- Audit adjustments: Where an ATO audit finds discrepancies and the assessed amount goes up, GIC applies to the new, larger amount.
- Missed payment plan instalments: If a business defaults on an ATO payment plan, GIC keeps accruing on the full outstanding balance and not just the instalment that was missed.
How Does GIC Compound?
GIC compounds daily, which means interest is charged on both the original debt and on GIC that has already accrued. At the current rate of 11.51% per annum for the October to December 2026 quarter, a debt left unpaid for a full year at that rate would cost more than 12% once daily compounding is taken into account.
ATO GIC Rates: Current Rate, the Rate Formula, and Rate History
The GIC rate is not fixed, and anyone carrying ATO debt across several months will usually see more than one rate applied to the same balance.
How the GIC Rate Is Set
The GIC rate is set each quarter by the ATO under section 8AAD of the Taxation Administration Act 1953. It is calculated as the 90-day Bank Bill rate plus 7 percentage points, and it is expressed as an annual rate, with the daily rate worked out by dividing the annual rate by the number of days in the calendar year.
Because it is tied to the Bank Bill rate, the GIC rate rises and falls with broader interest rate movements. It is updated on 1 January, 1 April, 1 July and 1 October each year, and the ATO generally announces the rate for the next quarter around two weeks before that quarter begins.
Current GIC Rate
The GIC rate for the quarter 1 October 2026 to 31 December 2026 is 11.51% per annum (0.03153425% per day). Source: ato.gov.au/tax-rates-and-codes/general-interest-charge-rates.
That is up from 11.43% per annum in the July to September 2026 quarter, and it is the highest quarterly rate the ATO has applied in the past two years.
GIC Rate History
The table below sets out the GIC rates for the last eight quarters as published by the ATO.
| Quarter | Annual Rate | Daily Rate |
| Q4 2026 (October to December 2026) | 11.51% | 0.03153425% |
| Q3 2026 (July to September 2026) | 11.43% | 0.03131507% |
| Q2 2026 (April to June 2026) | 10.96% | 0.03002740% |
| Q1 2026 (January to March 2026) | 10.65% | 0.02917808% |
| Q4 2025 (October to December 2025) | 10.61% | 0.02906849% |
| Q3 2025 (July to September 2025) | 10.78% | 0.02953425% |
| Q2 2025 (April to June 2025) | 11.17% | 0.03060274% |
| Q1 2025 (January to March 2025) | 11.42% | 0.03128767% |
Source: Australian Taxation Office, General interest charge (GIC) rates.
How the ATO Calculates GIC on Your Debt
GIC is calculated daily using the rate that applies to each day the debt is outstanding. The formula is:
Daily GIC = Outstanding debt x (Annual GIC rate / 365)
The total GIC for a period compounds, because GIC charged on one day becomes part of the balance on which GIC is charged the next day, and this continues until the full amount is paid.
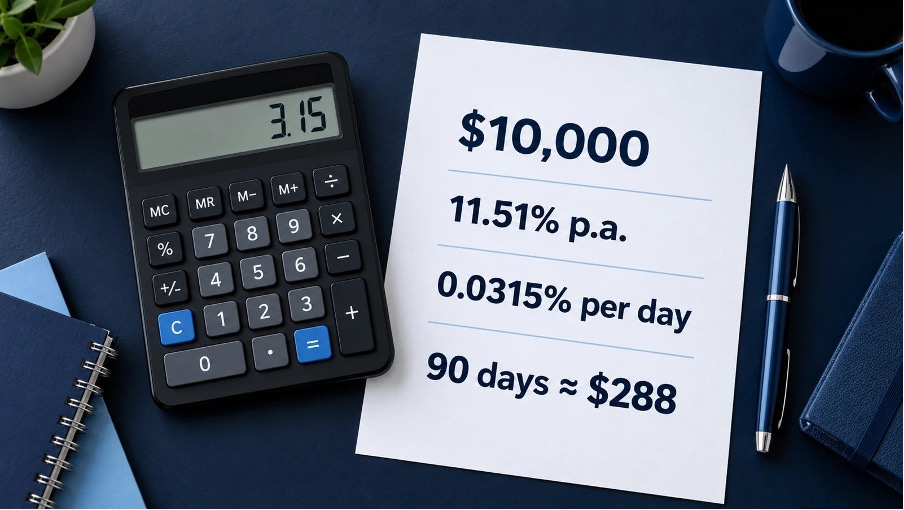
The following example uses the October to December 2026 rate:
- Debt amount: $10,000 of overdue tax.
- GIC rate: 51% per annum (1 October to 31 December 2026).
- Daily rate: 51% / 365 = 0.0315% per day.
- Daily GIC: $10,000 x 0.0315%, or roughly $3.15 on day one.
- Over 90 days: roughly $288 in GIC once daily compounding is included.
Your actual GIC is calculated at the rate applicable to each day the debt was outstanding, so if the debt spans more than one quarter, different rates apply to different periods.
GIC vs Shortfall Interest Charge (SIC)
GIC and the Shortfall Interest Charge (SIC) are both ATO interest charges, but they apply in different situations. GIC is charged for late payment of an outstanding tax debt.
SIC, on the other hand, applies when there is a shortfall in tax that was under-reported or incorrectly calculated, which often arises during an ATO audit or when a taxpayer amends a return after it was originally lodged. SIC is charged on the shortfall amount for the period between when the tax was originally due and when the assessment is amended.
SIC is calculated at the GIC rate less 4 percentage points, which puts it at 7.51% per annum (0.02057534% per day) for the October to December 2026 quarter, and like GIC it compounds daily. Payment of SIC falls due 21 days after the ATO issues the notice of amended assessment, and if it is still unpaid after that date GIC is applied automatically.
| Feature | GIC | SIC |
| Applies to | Overdue tax debts | Tax shortfalls found on amendment |
| Rate (October to December 2026) | 11.51% p.a. | 7.51% p.a. |
| Rate formula | 90-day Bank Bill rate + 7% | 90-day Bank Bill rate + 3% |
| Compounding | Daily | Daily |
| Tax deductible from 1 July 2025 | No | No |
Can the ATO Remit or Waive GIC?
GIC can be remitted in full or in part, although remission is assessed case by case and is never automatic. The ATO’s approach is set out in Practice Statement Law Administration PS LA 2011/12, Remission of general interest charge.
Circumstances Where GIC Remission Is Granted
The ATO may consider remitting GIC in cases such as:
- Financial hardship: Where a business is experiencing genuine financial hardship, supported by detailed evidence of its financial position.
- Special circumstances: Where events outside the taxpayer’s control, such as serious illness or a natural disaster, prevented timely payment.
- ATO administrative error: Where the delay in payment was caused by an error or delay on the part of the ATO.
Under PS LA 2011/12, the Commissioner must also be satisfied that it would be fair and reasonable to remit the GIC given all the circumstances. Where the delay was caused by the taxpayer, the ATO will look at whether the business took reasonable steps to reduce the impact of those circumstances, and the practice statement specifically refers to steps such as realising assets or seeking finance.
Can You Apply for Remission After Paying?
Yes. This is a common misconception, but you can apply for GIC remission even after you have already paid the charge. If the Commissioner approves remission of an amount that has already been paid, the ATO will issue a refund of that amount, although it may first apply the credit to any other outstanding tax debts.
Written Applications Versus Phone Applications
Written remission applications typically receive more thorough consideration than phone requests, because they allow the taxpayer to set out the full circumstances and supporting evidence in detail. A registered tax agent or accountant can prepare and submit a written application on behalf of the business.
How to Apply for GIC Remission
To request remission, set out the reasons for the request and provide supporting documentation. Applications can be made:
- Through ATO online services for individuals, accessed via myGov.
- Through Online services for business.
- Through a registered tax agent, who can lodge the request on your behalf.
For a broader look at whether the ATO will write off or remit your tax debt, see our dedicated guide.
ATO GIC vs Commercial Tax Debt Loan Costs
Many business owners compare ATO GIC with the interest rate on a commercial tax debt loan. Because GIC is no longer tax deductible from 1 July 2025, the effective cost of carrying GIC is now the full pre-tax rate, which makes commercial loan alternatives relatively more attractive for businesses in a tax-paying position.
How Commercial Tax Debt Loans Work
The structure of commercial tax debt loans depends on the lender and the product, but most will include:
- Fixed or variable interest rates
- Set repayment terms
- Monthly repayments
- No daily compounding GIC charges from the ATO on the debt that is cleared
- Potential tax deductibility of interest, depending on the purpose of the loan
How GIC Compares in Real Cost
A business carrying a large ATO debt on a long-term payment arrangement can end up paying substantial amounts in non-deductible interest while the debt reduces slowly. GIC still applies under an ATO payment plan, so costs continue to build for as long as any part of the debt remains unpaid.
By contrast, a commercial tax debt loan may offer a lower rate than the current GIC rate, and where the loan is used for business purposes the interest may be deductible, which reduces its after-tax cost further.
Options When You Cannot Pay ATO GIC
Ignoring ATO interest charges rarely improves anything. A business that is falling behind on GIC, or on an existing payment arrangement, generally has more options available and gets a better result when it acts early rather than waiting for the ATO to escalate.
Renegotiate Your ATO Payment Arrangement
The ATO may agree to revise an existing payment plan if your business circumstances have changed and the business is still viable but under short-term pressure, although it will usually want updated cash flow and liability information. Note that a payment plan does not pause GIC, and the charge continues to accrue on the outstanding balance even during an active arrangement. Our guide to ATO payment plan eligibility explains what to do if you do not qualify.
Apply for GIC Remission with the ATO
The ATO may remit part or all of the GIC charged, but it will usually expect the business to show it is actively resolving the debt, including lodging outstanding returns and keeping current obligations up to date.
Refinance the Tax Debt with a Commercial Tax Debt Loan
Refinancing the ATO debt into a commercial lending product means GIC stops accruing on the debt that has been cleared, and the effective borrowing cost may well be lower, more so now that GIC is no longer deductible. Repayments can also be lower because tax debt loans can run over longer terms than an ATO payment plan.
Final Thoughts
The ATO General Interest Charge is a daily compounding charge on unpaid tax that is reset each quarter, currently sits at 11.51% per annum and, since 1 July 2025, can no longer be claimed as a deduction. It continues to accrue during a payment plan, and while remission is available in some circumstances, it is not guaranteed.
For businesses carrying ATO debt, the key is to act early and compare the real cost of each option. Dark Horse Financial works with a large panel of lenders to match each business with the lender whose policy fits its circumstances, and we can help you assess whether refinancing makes sense. Explore our tax debt loans to find out more.
Frequently Asked Questions
Yes, the ATO can remit part or all of the General Interest Charge, though each request is assessed on its own facts. You will usually need evidence of financial hardship, circumstances that were outside your control or an administrative error by the ATO, and the Commissioner has to be satisfied that remission is fair and reasonable in all the circumstances.
No. From 1 July 2025, businesses and individuals can no longer claim a tax deduction for the ATO General Interest Charge or Shortfall Interest Charge. This applies to charges incurred in income years starting on or after 1 July 2025, regardless of when the original debt arose, and has increased the effective cost of carrying tax debt.
Yes, GIC compounds daily. Interest is charged not only on the original tax debt but also on GIC that has already accrued, which can cause the balance to grow quickly over time. At 11.51% per annum, the effective annual cost of a debt left unpaid for a full year exceeds 12%.
The ATO sets the GIC rate each quarter under section 8AAD of the Taxation Administration Act 1953. The rate is the 90-day Bank Bill rate plus 7 percentage points, expressed as an annual rate. It is updated on 1 January, 1 April, 1 July and 1 October, so it moves in line with broader interest rates.
Yes. Because GIC compounds daily, any GIC that has accrued and remains unpaid becomes part of the balance on which further GIC is calculated. This is why a tax debt can grow faster than the headline annual rate suggests, particularly when repayments do not cover the interest being charged.
GIC is interest on tax that was not paid by the due date and it accrues every day until the debt is cleared. A failure to lodge on time penalty is a different thing altogether, being an administrative penalty for lodging a return or statement late, calculated in penalty units, and it can apply even where no tax is owed.
No. GIC and SIC incurred in income years starting on or after 1 July 2025 are not tax deductible, so GIC charged in 2026 cannot be claimed as a deduction. Businesses therefore bear the full cost of GIC, which is now 11.51% per annum for the October to December 2026 quarter.
Sources and Methodology
GIC and SIC rates in this article were taken directly from the ATO’s published quarterly rates tables and were current as at 12 October 2026. Worked examples use the October to December 2026 rate and are illustrative only.
- Australian Taxation Office, General interest charge (GIC) rates: ato.gov.au/tax-rates-and-codes/general-interest-charge-rates
- Australian Taxation Office, Shortfall interest charge (SIC) rates: ato.gov.au/tax-rates-and-codes/shortfall-interest-charge-rates
- Australian Taxation Office, PS LA 2011/12 Remission of general interest charge: ato.gov.au/law/view/document?docid=PSR/PS201112/NAT/ATO/00001
- Taxation Administration Act 1953 (Cth), section 8AAD
- Treasury Laws Amendment (Tax Incentives and Integrity) Act 2025 (Cth)
- Australian Taxation Office, guidance on the deductibility of GIC and SIC from 1 July 2025
- HopgoodGanim Lawyers, commentary on GIC remission applications
Disclaimer: This article is for general informational purposes only and does not constitute financial, tax, or legal advice.
Get a Tax Debt Loan for Your Business
If you're struggling with late tax payments or need a tax debt loan, you should consult with a lending professional like Dark Horse Financial. We’re experts in tax debt lending, and we’ll help you face ATO debt head-on and avoid GIC.