A caveat loan is a short-term business loan secured by a caveat lodged on your property’s title. Approval can be as fast as 24 to 48 hours, and settlement can follow within 24 to 72 hours of approval, depending on the lender. A second mortgage is a registered loan that sits behind your existing first mortgage and generally offers larger amounts over longer terms of one to five years or more. In any caveat loan vs second mortgage comparison, the right choice comes down to how quickly you need the funds, how much you need and how you intend to repay.
Introduction
Caveat loans and second mortgages are two of the most common ways a business owner can use the equity in a property to fund the business, and they are also two of the most commonly confused. Most people who have heard of both could not say precisely how they differ, and the confusion is understandable. Both are secured by property, both come mostly from private lenders, and both are assessed on equity and the credibility of the exit strategy rather than on a credit score, so on paper they look interchangeable when in practice they are not.
Private lending is not the whole story either. A lender that sells only caveat loans, or only second mortgages, has no reason to mention the third path, an ordinary bank or non-bank business loan, yet for a business with a few weeks up its sleeve that is often the better outcome. Dark Horse Financial arranges all three through a large panel of banks, non-bank lenders and private financiers, so what follows is the comparison a broker who deals in all three would actually run.
Key Takeaways
- A caveat loan can be approved in as little as 24 to 48 hours, with settlement following within 24 to 72 hours of approval depending on the lender, and it runs for 2 to 24 months, so it is built for the urgent, short-lived funding gap.
- A second mortgage takes 1 to 3 weeks to put in place, runs for 1 to 5 years or longer, and will usually be the larger of the two.
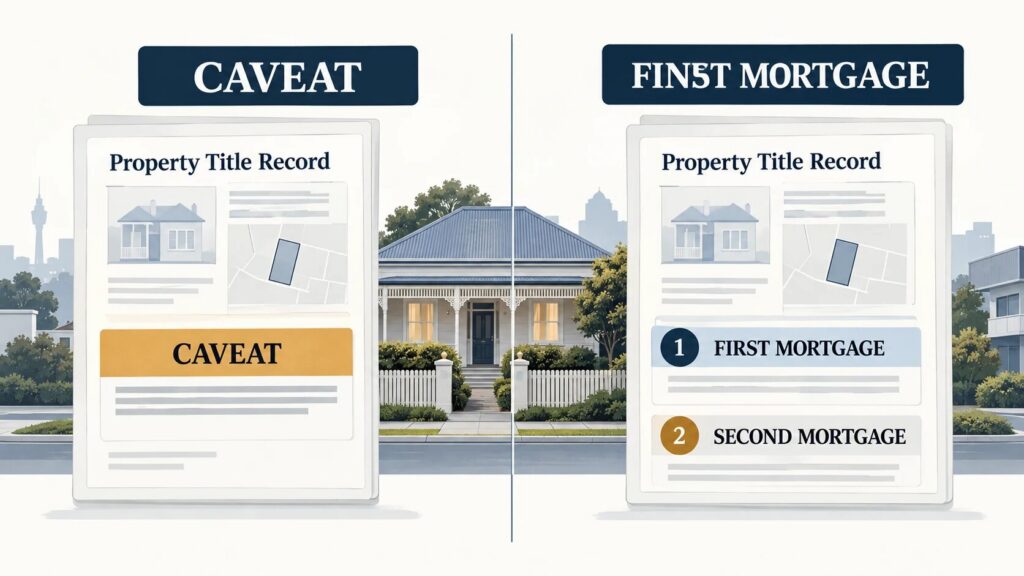
- The security is different. A second mortgage is registered on title behind (not on top of) your existing first mortgage, whereas a caveat loan relies on a caveat lodged against the title with no mortgage registered at all.
- Neither product is decided on your credit score. Equity in the property and a credible exit strategy carry the assessment.
- A non-bank business loan assessed from bank transaction data can settle within 24 to 48 hours without tying up property security, so it belongs in the comparison even when the need is urgent, while a bank loan still suits the business with more time on its side.
- Because Dark Horse Financial has a large panel of lenders across all three categories, the comparison can be a genuine three-way one.
What Is a Caveat Loan in Australia?
A caveat loan is a short-term business loan secured against property, with one distinguishing feature: instead of registering a mortgage, the lender lodges a caveat on the title. A caveat is a legal notice recorded against the property. While it sits there the owner cannot sell, refinance or otherwise deal with the property, and it comes off once the loan is repaid.
Terms run anywhere from 2 to 24 months. Because lodging a caveat is a far simpler exercise than registering a mortgage, approval can come through in 24 to 48 hours where the property position is clear, with settlement following within 24 to 72 hours of that depending on the lender, and that speed is the whole reason caveat loans in Australia get used the way they do: to clear an ATO debt before a payment arrangement defaults, to cover a payroll that falls due before a large invoice is paid, or to settle a supplier who has stopped supplying.
The assessment looks at two things above everything else, the equity in the property and the exit, meaning exactly how the loan will be repaid when the term ends. Being a private lending arrangement, there is generally no credit assessment or income verification of the kind a bank would require. Loan amounts for a private lender caveat loan typically range from $50,000 to $1 million, depending on the lender and the security offered.
One legal note. Caveats and mortgages are governed by state-based Torrens title legislation, such as the Real Property Act 1900 in New South Wales and the Transfer of Land Act 1958 in Victoria, so lodgement procedures differ from state to state even though the concept is the same everywhere. This page is general information, not legal advice.
How a Caveat Loan Works
There are not many steps, and that is the point. The lender takes the application and the property details, runs a title search to confirm who owns the property, what is already registered against it and how much equity is left, prepares the loan documents, lodges the caveat with the land titles office in the relevant state or territory, and releases the funds. Where nothing on title complicates matters, approval commonly lands inside 24 to 48 hours and settlement follows within 24 to 72 hours of approval, though the exact timing varies from lender to lender.
What the caveat does is put the lender on notice ahead of any later dealing with the property. What it does not do is transfer ownership or hand the lender the registered rights of a mortgagee. The approval question is less about what the credit file says and more about how the loan gets repaid, so expect the lender to test the exit, whether that is a refinance into a longer facility, the sale of the property or another asset, or receivables due to land inside the term.
Registering the Caveat
The document lodged is a caveat form, supported by the loan agreement, recording the lender’s claimed interest in the land. Compared with a full mortgage it is quicker and simpler to lodge, it does not need the first mortgagee’s consent, and it leaves the ranking of any mortgage already on title exactly where it was. Do not mistake simpler for informal, though. It is a legally binding notice, and while it stays on title the owner cannot deal with the property.
Speed to Settlement
Two clocks run on a caveat loan: the time to approval, as fast as 24 to 48 hours, and the time from approval to settlement, as fast as 24 to 72 hours after that. Both vary between lenders, and both assume a clean title and a borrower who has their information ready. It stretches when there is a dispute over the title, when another caveat is already sitting on the property and has to be dealt with first, or when the property and identity documents the lender asks for take days to surface. In our experience the lender is rarely the bottleneck; incomplete paperwork is.
What Is a Second Mortgage in Australia?
A second mortgage is a registered mortgage that ranks behind the first mortgage already on the property. Being registered rather than lodged as a caveat gives the lender a stronger security position, and a stronger position is what lets the lender advance more money for longer, generally 1 to 5 years and sometimes beyond. If the property is ever sold, the first mortgage lender, usually a bank, is paid first, and the second mortgage lender is repaid out of whatever equity remains.
A second mortgage business loan is often used when business owners need additional funding but do not want to refinance their primary mortgage. It allows them to unlock available equity in their property without disturbing their existing home or commercial loan, and that matters a great deal when the first mortgage was written on terms the borrower would struggle to get again.
The typical uses are longer-horizon ones, such as funding an expansion, folding several expensive short-term debts into one longer facility, or financing a project whose return arrives over years rather than weeks. How high a combined loan-to-value ratio a lender will go to varies between lenders and depends on the property type and its location, but most lenders cap out at a maximum of 75% LVR.
How a Second Mortgage Works
A second mortgage takes longer to put in place than a caveat, and the reasons are mechanical rather than bureaucratic. There is formal mortgage documentation to prepare, in most cases a valuation to obtain, and frequently the first mortgagee’s consent to secure, so the approval window is typically 1 to 3 weeks rather than days. Once the lender has assessed the property value and the borrower’s position, the second mortgage is registered on title behind the first lender and funds are released.
None of this touches the first mortgage. Its rate, its repayments and its term carry on exactly as before, with the second mortgage simply registered behind it. One practical difference from caveat lending is the size of the lender pool, which for second mortgages stretches from private financiers through to some non-bank lenders and gives a broker more room to find the lender whose policy actually suits the borrower.
Priority Behind the First Mortgage
Second ranking means exactly what it says. Should the property be sold, or the borrower default and the property be realised, the first mortgagee is paid out in full before the second mortgagee sees a dollar, so the second lender’s recovery rests entirely on whatever equity is left over. That is why second mortgage lenders in Australia watch the combined loan-to-value ratio so closely, and why the first mortgagee’s consent is so often required.
Typical Terms and Loan Amounts
Terms generally run from 1 to 5 years, sometimes longer. Amounts are generally larger than a caveat loan against the same property, because registered security supports a bigger advance against the same equity, though each lender sets its own policy on term and amount.
Caveat Loan vs Second Mortgage: Head-to-Head Comparison
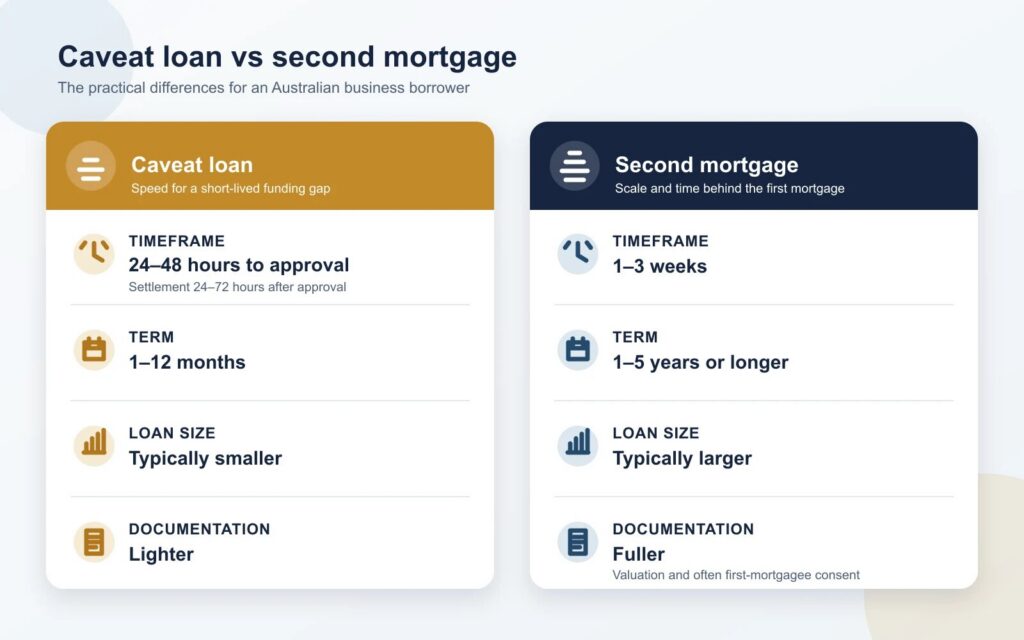
Set side by side, the difference between caveat loan and second mortgage products comes down to four things: speed, the type of security, the term and the job each is suited to. They share a great deal, since both are property-secured and both are assessed on equity and exit rather than credit score, yet using one feels nothing like using the other.
| Feature | Caveat Loan | Second Mortgage |
|---|---|---|
| Security type | Caveat lodged on the property title | Registered mortgage ranking behind the first mortgage |
| Typical timeframe | Approval in as little as 24 to 48 hours; settlement within 24 to 72 hours of approval | 1 to 3 weeks |
| Typical term | 2 to 24 months | 1 to 5 years or longer |
| Typical loan size | Smaller, matched to a short-term need | Larger, supported by registered security |
| Documentation required | Minimal; property details, identification and exit strategy | Fuller; mortgage documents, valuation, often first-mortgagee consent |
| Best suited for | Urgent tax debt, supplier payments, bridging a settlement gap | Expansion, consolidation, longer-horizon projects |
Where they overlap is the middle ground, the moderate amount needed on a moderate timeline, and there the right answer is often neither of the two products above.
When a Bank or Non-Bank Business Loan Beats Both Options
Most articles on this subject are written by private lenders who sell one or both of the products above, so the comparison ends where their product range ends. Ours does not need to. Dark Horse Financial’s panel spans banks, non-banks and private financiers, which means we can put all three funding paths next to each other and match a business to the one lender whose policy fits its circumstances, instead of defaulting to a private lending recommendation because that is all that is on the shelf.
That statement holds for a bank, where fuller documentation, a longer approval window and a full credit assessment mean it is rarely the answer when the money is needed this week. Non-bank business lending has moved a long way from that model. Many non-bank lenders now assess serviceability from a read-only view of the business’s bank transaction data, and because the process is software-driven rather than manually underwritten, it can be both reliable and fast, with approval and settlement possible within 24 to 48 hours. A business with the trading history to support that kind of read can often get a better outcome from an unsecured non-bank facility than from tying up a property behind a caveat loan or a second mortgage. A traditional bank loan still earns its place for the business with time on its side, wanting a longer term and a repayment structure built around actual cash flow.
The judgement is about fit, not price. A caveat loan that clears an ATO debt before a director penalty notice crystallises is doing something a bank cannot do in the time available, and the mainstream loan earns its place for the business that has time on its side. We cover the short end of that spectrum in our guide to bridging finance for business and the long end under second mortgage business loans, and if you would like a view on which path suits you, speak with our team for a same-day comparison across all three.
Benefits and Drawbacks of Each Option
The trade-off is easy to state and harder to live with. Caveat loans win on speed and lose on size and term. Second mortgages win on scale and duration and lose on time to settle. Neither is better in the abstract, so the right one is whichever lines up with the problem in front of you.
Caveat Loan: Benefits and Trade-offs
Speed is the headline benefit, with approval in as little as 24 to 48 hours and settlement within 24 to 72 hours of that, but it is not the only one. Documentation is lighter than for any registered facility, the funds can go to almost anything from working capital and supplier payments through to tax debt and bridging a settlement gap, and because the assessment turns on equity and exit, a borrower with a blemished credit file or a short trading history can often still qualify.
Against that sit shorter terms of 2 to 24 months, smaller amounts, and a cost of funds that reflects both the speed and the fact that the security is not a registered mortgage. Caveat loan business finance therefore only makes sense with a clear, realistic exit in view from day one. It is a tool for a specific short-term job, not a standing source of working capital.
Second Mortgage: Benefits and Trade-offs
Here the case rests on size and time. Larger amounts, terms of 1 to 5 years or more, and a broader pool of lenders, which improves the odds of finding one whose policy suits both the property and the borrower. The first mortgage is left untouched, so a borrower sitting on a favourable first mortgage does not have to surrender it to get at the equity behind it.
The price of all that is patience. Approval takes 1 to 3 weeks, the documentation is fuller, and the first mortgagee’s consent is frequently needed, which adds time and is not always forthcoming. The second-ranking position also makes lenders conservative on the combined loan-to-value ratio, so the amount actually available can come in below what the headline equity figure suggests.
When to Use a Caveat Loan vs a Second Mortgage
Two questions settle most cases: how urgent is it, and how much is it? A deadline measured in days, and an amount that can be repaid or refinanced within months, points to a caveat loan, unless the business has the bank transaction history to support a fast non-bank loan instead, in which case that is often the better outcome since it does not tie up the property at all. A larger amount with repayment stretching across years points to a second mortgage. And whenever a bank’s fuller documentation and longer approval window can be accommodated, a bank loan stays in the frame too.
Best-Fit Scenarios for Caveat Loans
Business owners might consider a caveat loan when funding is needed within days, the business faces urgent ATO debts or supplier payments, a property has available equity but time is limited for formal loan processing, the funding need is temporary and can be repaid quickly, or a settlement gap needs bridging between a sale and a purchase. The common thread is a clear exit. Read the caveat loan eligibility criteria before applying, since most of what slows a caveat settlement down can be dealt with in advance.
Best-Fit Scenarios for Second Mortgages
A second mortgage is more appropriate when the business needs a larger loan amount for growth or investment, the borrower has strong equity and steady income, there is sufficient time to complete the registration and approval process, the business seeks a longer repayment period, or several short-term debts are being consolidated into a single facility. Think of the business buying a second premises, or the one carrying three expensive short-term facilities that wants them consolidated on a term it can actually service, without touching a first mortgage that is working well.
How to Choose the Right Option for Your Business
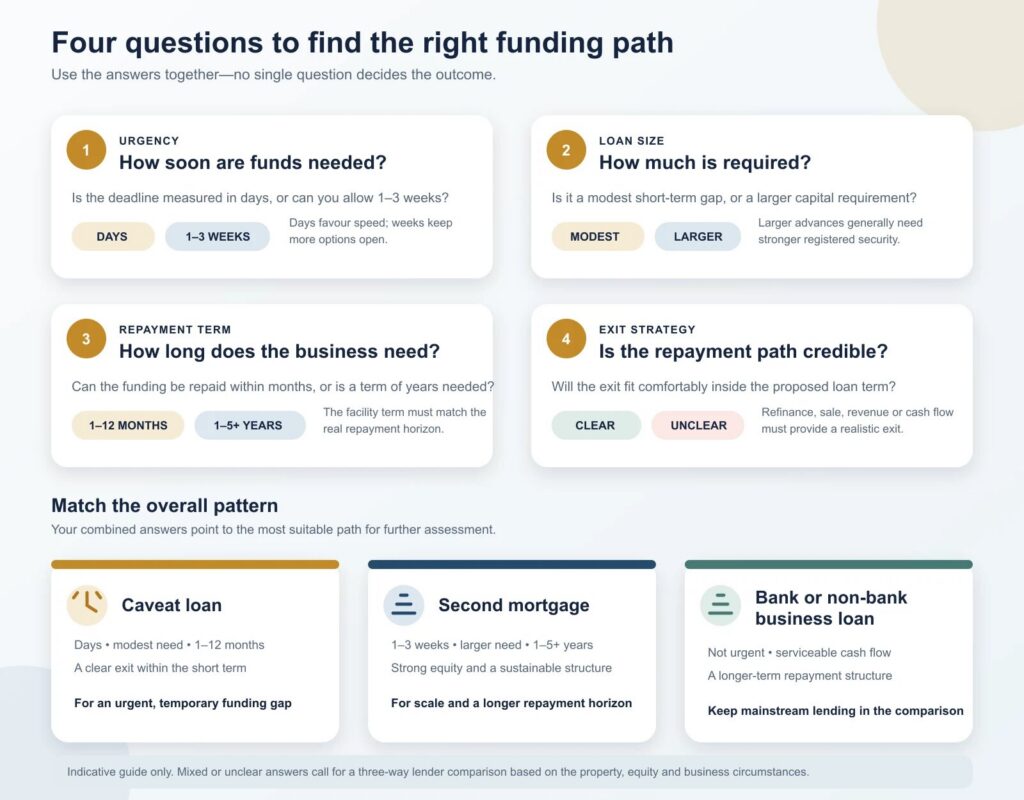
Four questions do most of the work. How urgent is the need, in days or in weeks? How large is the requirement relative to the equity actually available in the property? What repayment horizon does the business realistically need, months or years? And does the exit, whether that is a refinance, a sale or incoming revenue, fit comfortably inside the loan term on offer, or is it being made to fit?
Answer those honestly and one product usually stands out. Urgent, modest, short and with a defined exit is caveat loan territory, unless the business can support a fast non-bank loan on its bank transaction history, in which case that is worth putting first since it needs no property security at all. Larger, longer and less time-critical is second mortgage territory. Not urgent at all, with a business that can meet a bank’s standard serviceability criteria, is traditional bank territory, and it is surprising how often a fast non-bank option turns out to be the right answer for a business that walked in asking about a caveat loan.
Whatever the answer, get it from a broker who can place all three. A private lender offering one product can only ever recommend one product.
FAQs
The security and the timeframe. A caveat loan is protected by a caveat, a legal notice lodged on the property title rather than a registered mortgage, and it settles in days with terms of 2 to 24 months. A second mortgage is registered on title behind the existing first mortgage, takes 1 to 3 weeks to arrange, and generally provides larger amounts over 1 to 5 years or more.
Approval can be as fast as 24 to 48 hours, and settlement can follow within 24 to 72 hours of approval, depending on the lender, because lodging a caveat is far simpler than registering a mortgage. It takes longer when there is a title dispute, another caveat on the property, or incomplete property and identification documents, so have everything ready at the outset.
No. It is registered behind the first mortgage, and the first mortgage’s interest rate, repayments and term all carry on unchanged. The first mortgagee is often asked to consent before the second mortgage can be registered, and it keeps first claim on the property if the property is ever sold or realised, with the second lender paid from what remains.
There is no fixed answer, because cost depends on the loan size, the term, the security position and the lender involved. Caveat loans are priced for speed and short terms. Second mortgages are priced for a second-ranking registered position. A fast, unsecured non-bank loan assessed on bank transaction data can be competitively priced too, and where the timeline allows a bank’s full assessment, a traditional bank loan may well be the lower-cost path.
Yes, and this is one of the most common reasons businesses choose one. A second mortgage releases equity in a property while the first mortgage stays exactly as it is, with no full refinance triggered. That matters when the first mortgage is on terms you would not get again today, or when the business wants additional capital without restructuring its primary facility.
A non-bank business loan is worth considering whenever the business has the bank transaction history to support a fast, software-driven serviceability assessment, since approval and settlement can land within 24 to 48 hours without any property security involved. A traditional bank loan suits the business that has time for a fuller, standard credit assessment and wants the longest available term. Dark Horse Financial compares all three paths, caveat, second mortgage and mainstream lending, across a large panel of lenders and matches your business to the lender whose policy fits.
Conclusion
Strip everything else away and the difference between a caveat loan and a second mortgage is speed against scale. A caveat loan puts money in the account within days for a short, defined purpose. A second mortgage releases a larger amount over a longer term and leaves the first mortgage alone. And a business with the bank transaction history to support it should also weigh a fast, unsecured non-bank loan, which can settle just as quickly without tying up property at all, while a traditional bank loan still deserves its place for the business that is not under time pressure.
Choosing well means matching the product to the urgency, the size, the horizon and the exit rather than taking whichever product happens to be on offer. Dark Horse Financial works across a large panel of banks, non-bank lenders and private financiers, so we can compare all three paths and match your business to the one lender whose policy fits. If you are weighing up property-backed funding, get a same-day comparison from our team and we will set out the options plainly.
Disclaimer: Loans and their accompanying benefits are available only to those who qualify for them and have been approved. Though we put a lot of care into writing this article, the information presented within is general and doesn’t consider your unique situation. It is not meant to serve as a substitute for professional advice, and you should not rely on it solely for any major financial decisions. You should always consult with a professional when you’re dealing with finance, tax, and accounting matters.
Sources and Methodology
This article was prepared by Dark Horse Financial from its experience arranging caveat loans, second mortgage business loans and mainstream business finance for Australian businesses, and figures for settlement times, terms and loan sizes are indicative of current market practice rather than a guarantee from any lender. Legal references were checked against the following sources (non-clickable):
- Real Property Act 1900 (NSW), legislation.nsw.gov.au
- Transfer of Land Act 1958 (Vic), legislation.vic.gov.au
- Land Title Act 1994 (Qld), legislation.qld.gov.au
- Australian Securities and Investments Commission, Moneysmart, moneysmart.gov.au
Choose Between a Caveat Loan and a Second Mortgage
Caveat loans can settle quickly, while second mortgages often suit longer terms and larger amounts. Tell us how much you need and by when, and we’ll compare both property backed options for your situation.