Direct Answer
Lenders don’t just take the bottom-line figure on your tax return at face value when assessing self-employed home loan income. They weigh financial history, add-back adjustments and business stability together before deciding what you can borrow, drawing on tax returns, BAS, bank statements and accountant-prepared financials via a Full-Doc or Low-Doc pathway, whichever suits how complete your paperwork is. Most lenders want one to two years of trading history. Under 12 months usually means an automatic decline, unless you’ve changed entity structure or can show continuity of industry experience.
Introduction
Getting a home loan when you’re self-employed involves a more document-heavy process than it does for PAYG employees. A lender can’t just glance at a payslip and move on: they need to verify that your income is stable enough to service a loan over time, so sole traders, company directors and partners in a business all get asked to prove income in ways an employee never has to.
And it’s not a one-size-fits-all process. Self-employed income assessment differs from lender to lender: some weigh add-backs more generously, others are stricter on trading history, and a few simply won’t touch certain industries. That’s why panel breadth matters so much when you’re self-employed and shopping for a home loan. Below: the documents you’ll need, the five factors lenders actually assess, why applications get knocked back, and how to put your best file forward, including how home loans in Australia generally work for borrowers outside standard PAYG employment.
Key Takeaways
- Most lenders treat one to two years of self-employed trading history as the benchmark, and under 12 months can mean an automatic decline at many lenders, no matter how strong the income looks. Lender selection is important.
- Three to six months of bank statements is the usual ask, whichever pathway you apply through.
- BAS documentation generally runs six to twelve months (two to four quarters). A few lenders will take as little as two quarters, but don't assume that's the norm.
- Depreciation, one-off expenses, owner superannuation above the minimum: these add-backs can lift your assessable income well above the net profit figure on your tax return.
- Because self-employed income policy varies so much lender to lender, Dark Horse prioritises lender selection based on policy to match your circumstances, drawing from a large panel of lenders.
The Basics of Self-Employed Mortgage Applications
A self-employed mortgage application is judged differently to a standard PAYG loan, because there’s no regular payslip to point to. Lenders look instead at whether your income is stable enough, and likely to continue, to service the loan over its full term, which means closer scrutiny of your business financials and supporting documents than a salaried applicant ever faces.
For lender purposes, “self-employed” generally covers sole traders, company directors, and partners holding a meaningful ownership stake in the business.
What lenders are really pricing for is income variability, not the industry you work in, since earnings that move with business performance and broader market conditions are inherently harder to predict than a fixed salary. The trading structure you operate under (sole trader, company, trust or partnership) also determines which documents get requested, since a company’s financials look different to a sole trader’s tax return. Because policy on this point varies lender to lender, Dark Horse prioritises matching the right policy fit to a business owner’s circumstances to ensure a strong probability of approval.
Why Is Income Verification Important?
Income verification isn’t lender box-ticking: it’s a legal requirement. Credit providers in Australia must comply with the responsible lending conduct obligations set out in Chapter 3 of the National Consumer Credit Protection Act 2009, with ASIC’s Regulatory Guide 209 setting out what “reasonable inquiries” and “reasonable verification” look like in practice.
In practical terms, this protects both sides of the transaction: the lender from writing a loan that can’t be serviced, and you from over-committing to repayments your income won’t support long term. Self-employed income is simply harder to verify than a payslip that arrives the same amount, on the same day, every fortnight, which is the whole reason the extra scrutiny exists.
What Documents Do Self-Employed Borrowers Need for a Home Loan?
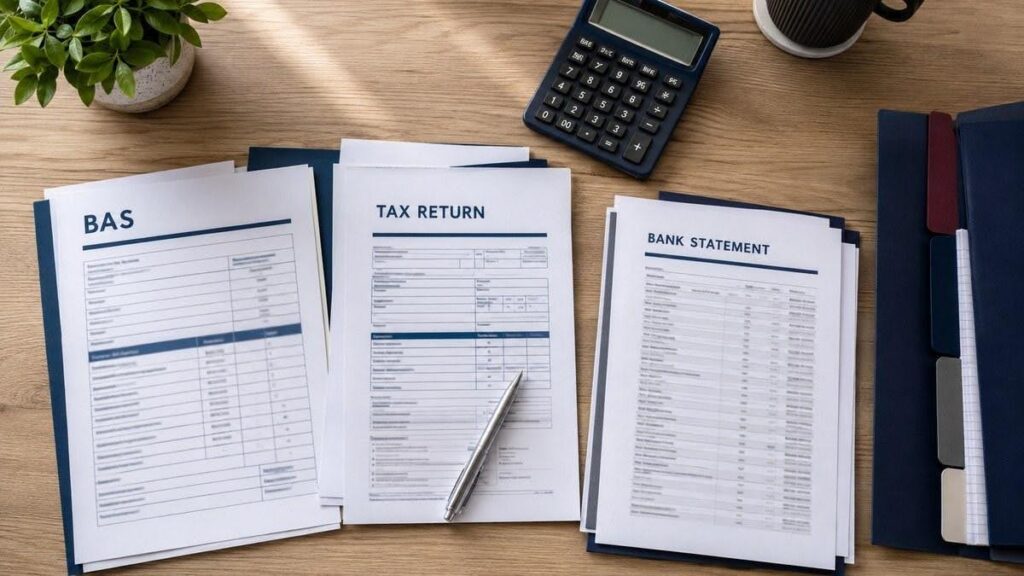
The self-employed mortgage documents Australia lenders ask for fall into two broad pathways, and which one applies to you depends largely on how up to date your paperwork is.
| Document Type | Full-Doc Requirement | Low-Doc Requirement |
| Tax returns | 2 years personal and business (some lenders now accept 1 year; confirm current panel policy) | Generally not required |
| BAS | Not typically required | 6 to 12 months (2 to 4 quarters); 2 quarters accepted by only some lenders |
| ABN / business registration details | Not typically requested separately | Required, alongside quarterly BAS |
| Bank statements | 3 to 6 months | 3 to 6 months |
| Financial statements | 2 years, prepared by an accountant | Often replaced by an accountant’s letter/declaration or two quarters of BAS |
| Accountant’s declaration | Occasionally requested as a supplement | Typically requested when BAS is not available for income verification |
Full-Doc Self-Employed Loans
Two years of tax returns and financial statements: that’s the traditional Full-Doc requirement, and it still opens the door to the broadest panel of lenders and the sharpest pricing. Major banks now also offer a streamlined one-year financials pathway.
Low-Doc Self-Employed Loans
Low-Doc substitutes BAS, ABN details and bank statements for full tax returns, which suits applicants whose most recent year of paperwork isn’t finalised yet, a common scenario if your accountant hasn’t lodged this year’s return but your trading position is otherwise strong. Explore our low-doc home loan options to see which pathway fits your situation.
How Do Lenders Assess Self-Employed Income in Australia?
Lenders weigh five things together when assessing self-employed home loan income: income consistency, business viability, add-backs, industry risk, and documentation quality. No single factor sinks an application on its own, except missing the minimum documentation, which stops the assessment before it starts. Because policy weighting on these five factors differs across lenders, Dark Horse prioritises matching borrowers’ circumstances to the lender with the right policy fit from a large panel of lenders.
One pattern worth knowing: where income is inconsistent across two years, many lenders will assess against the lower figure rather than an average of the two. That’s not universal, though, and it’s not a hard rule for every lender: lender selection is paramount.
Add-backs are often where the real borrowing power hides. Here’s a simplified, illustrative example of how they can lift assessable income above the net profit shown on a tax return:
| Line Item | Reported Figure | Add-Back Adjustment | Adjusted Assessable Income |
| Net Profit | $95,000 | (none) | $95,000 |
| Depreciation | (none) | +$8,000 | $103,000 |
| One-off / Non-recurring Expense | (none) | +$6,500 | $109,500 |
| Owner Superannuation (above minimum) | (none) | +$4,200 | $113,700 |
| Adjusted Total | $113,700 |
Figures above are illustrative only and don’t represent actual client or lender data; they’re included to show how the add-back mechanism works, not to promise a specific outcome.

Income Consistency Over Time
Lenders typically compare two to three years of income to identify a trend, rather than judging a single strong (or weak) year on its own, sometimes averaging fluctuating earnings or assessing against the lower of the two years.
Business Viability
This comes down to revenue trend, profit margins, and cash-flow stability: profit on paper isn’t the whole picture if the cash isn’t actually moving through the business.
Add-backs and Non-Cash Expenses
Add-backs restore non-cash and one-off items, such as depreciation, one-off expenses and owner superannuation above the minimum, to net profit, revealing the cash genuinely available to service a loan (see the worked example above).
Industry Risk Profile
Seasonal businesses and industries such as construction commonly attract more conservative treatment from lenders, due to historical earnings volatility.
Income Documentation
How complete and consistent your documentation is directly affects which lenders on the panel will even consider the file, with official, verifiable records and accountant-prepared financials preferred over less comprehensive alternatives.
What Income Is Considered Reliable by Lenders for Self-Employed Loans?
Lenders generally look for self-employed income that’s consistent, documented, sustainable and sufficient.
Consistent means your income holds steady, or trends upward, across at least two financial years, sourced from an ongoing trading business rather than a one-off event. A climbing income trend is treated more favourably than flat income at the same average, even if the numbers look similar on paper.
Documented means it’s backed by matching tax and bank records rather than your word alone. Recurring trading income counts; a one-off capital gain or asset sale generally doesn’t, and rental or investment income can supplement your file but won’t replace trading income as the main evidence.
Sustainable means the lender believes the income is likely to continue, which is why business viability and industry factors get weighed alongside the numbers themselves.
Sufficient means it’s enough to cover the loan repayments on top of your other living expenses. Cash income without a paper trail generally can’t be counted toward any of this, no matter how real it is to you.
Common Reasons Self-Employed Income Is Rejected by Lenders
Most rejections trace back to one of four things: incomplete or outdated documentation, an inconsistent income trend, a short business history, or industry risk stacking up with a poor credit history. The good news is that every one of these is preventable with the right preparation, which is really what the tips section below is about.
Incomplete Documentation
Missing, partial or outdated financials are the single most common reason an application stalls before assessment even properly begins.
Inconsistent Income Trends
Income fluctuations, a declining revenue trend, or seasonal gaps that raise sustainability concerns lead most lenders to assess against the lower figure rather than giving you the benefit of an average. Mismatched figures between your BAS, bank statements and tax returns are another common trigger worth watching for.
Short Business History
Businesses trading for less than 12 months are typically declined automatically by mainstream lenders, regardless of how strong the income actually is. This is the flip side of the one-to-two-year trading history norm covered earlier. There are circumstances where business owners trading for less than 12 months can still be approved, though the number of lender options available will be greatly restricted.
Industry Risk or Poor Credit History
A higher-risk industry combined with an adverse credit history, including payment defaults or late payments, compounds the scrutiny you’ll face and shrinks the pool of lenders willing to even look at the file.
How Your Business Financials Affect Your Personal Home Loan Serviceability
This is where self-employed borrowers often get caught out: decisions on the business side of the ledger directly shape what a lender will approve on the personal home loan side. Your trading structure, how thoroughly your add-backs are documented, and any history of ATO debt all feed into the same assessment, whether you think of them as separate or not.
Unresolved ATO debt, in particular, can reduce your borrowing capacity or rule certain lenders out entirely, even where your personal credit file is otherwise spotless. How your business structures owner drawings or dividends also affects what actually counts as “income” for serviceability purposes, which catches a lot of business owners off guard.
This is exactly why it helps to have a broker looking at both sides of the file at once. Sequencing matters: resolving ATO tax debt before submitting a home loan application, for instance, can materially change the outcome, and it’s the kind of structural view a mortgage-only broker simply isn’t positioned to offer.
Tips for Strengthening a Self-Employed Mortgage Application
- Work with a broker experienced in self-employed lending who compares policy across multiple lenders, rather than applying blind to whichever bank you already have an account with.
- Get two years of financials together where you can. A streamlined one-year pathway now exists with some major banks, but two years still opens the widest range of options.
- Allow adequate time to prepare and update your financials, and get them finalised and lodged early rather than relying on estimates.
- Maintain clean bank statements, free of dishonours or other problematic transactions, and keep personal and business banking clearly separated for cleaner verification.
- Involve your accountant early to help prepare documentation, and deal with any ATO debt or adverse credit before you apply, not midway through the process.
FAQ
Full-Doc applicants are generally asked for business financial statements, ATO notices of assessment or tax returns, and bank statements (typically 3 to 6 months). Low-Doc applicants typically provide ABN and business registration details, quarterly BAS, bank statements, and an accountant’s letter in place of full tax returns.
Yes, through a Low-Doc pathway. Lenders typically want 6 to 12 months of BAS (2 to 4 quarters) plus 3 to 6 months of bank statements. Only a small number of lenders will accept as little as two quarters, so check this with your broker rather than assuming it applies generally.
Lenders look for income that’s consistent across at least two years, documented with matching tax and bank records, sustainable enough to likely continue, and sufficient to cover loan repayments alongside your other living expenses. One-off capital gains and undocumented cash income generally don’t count.
It’s difficult. Most mainstream lenders require one to two years of trading history and will decline applications under 12 months outright. Some non-bank lenders on a broader panel will still consider a file with strong compensating factors, such as a large deposit or directly relevant prior industry experience.
They add non-cash and one-off items, such as depreciation, one-off expenses and owner superannuation above the minimum, back onto the net profit shown on your tax return. This often reveals meaningfully more serviceable income than the bottom line suggests (see the worked example earlier in this article).
Yes. Unresolved ATO debt can reduce borrowing capacity or exclude certain lenders altogether, even with an otherwise clean credit file. This is one reason Dark Horse looks at resolving ATO tax debt as part of the same conversation as the home loan itself, rather than as a separate problem.
Conclusion
Getting approved as a self-employed applicant really comes down to one thing: presenting consistent, well-documented income to a lender whose policy actually fits your circumstances. That’s a harder match to make alone than it looks, which is exactly where Dark Horse’s dual focus on business and home lending, backed by a panel of 100+ lenders, does the heavy lifting for you. If you’re ready to see what your file looks like to the right lender, speak with our brokers about a dedicated self-employed home loan consultation.
Sources and Methodology
- National Consumer Credit Protection Act 2009 (Cth), Chapter 3, responsible lending conduct obligations.
- ASIC Regulatory Guide 209, Credit licensing: Responsible lending conduct.
- General lending-practice conventions (BAS periods, bank statement windows, add-back treatment) reflect common Australian broker-panel experience rather than a single citable source.
We Streamline the Process for Self-Employed Borrowers
If you’re self-employed and unsure of how to proceed with a home loan application, contact our team at Dark Horse Financial. We’ll simplify the process for you, ensuring you can secure the home of your dreams without hassle. We’ll also help you secure the best rates and terms for your situation.
Disclaimer
This article is general information only and doesn’t take into account your personal financial situation, needs or objectives. Loan products are subject to individual lender approval criteria. Speak with a Dark Horse broker or your own financial adviser before making a decision.