When a business needs funds quickly and the owner holds equity in property, a caveat loan is often one of the first options raised, but few people are clear on how it actually works. This guide answers the question of what is a caveat loan in Australia, and as a comprehensive guide it walks through how the process runs step by step, how a caveat loan compares with a second mortgage and a bank loan, what it is commonly used for, who is eligible, and how to take the next step.
Key Takeaways
- A caveat loan is short-term finance secured by a caveat lodged on a property's title, rather than by a registered mortgage.
- Lenders assess caveat loans mainly on the equity in the property and the strength of the exit strategy, not on years of trading history.
- Approval on straightforward caveat loan applications can be as fast as 24 to 48 hours, with settlement able to follow in as little as 72 hours after approval, depending on the lender.
- A caveat is an unregistered interest on title, while a second mortgage is a registered one, so the two products differ in speed, paperwork and typical term.
- Before applying, have a clear repayment plan in place, such as a property sale, a refinance or a confirmed incoming payment.
- If you do not hold suitable property equity or need longer-term funding, other business loan structures are likely to be a better fit.

What Is a Caveat Loan?
In property law, a caveat is a formal notice lodged on a property’s title register. It alerts anyone searching the title that another party claims an interest in the property, and it prevents further dealings on that title, such as a sale or new mortgage, from being registered without the caveat holder being notified or consenting.
A caveat loan relies on this same mechanism for its security. Rather than going through the longer process of registering a full mortgage and all of the documentation that comes with it, the lender lodges a caveat over the borrower’s property for the term of a short-term advance, and the caveat stays on the title protecting the lender’s position until the loan is repaid, when it is withdrawn.
The amount that can be borrowed is based mainly on the available equity in the property rather than on the borrower’s cash flow history or financial statements. Through Dark Horse’s lender panel, caveat loans can typically be arranged from $50,000 to $10 million, with the final amount depending on the property’s value, any existing debt registered against it, and the lender’s own policy.
Businesses and property owners tend to turn to caveat loans when funds need to be released quickly and they already hold equity, either unencumbered or under-leveraged, that they can offer as security. Many lenders are also comfortable with a caveat sitting behind an existing first mortgage, so the owner is not forced to refinance their whole loan to get access to a short-term amount.
How Does a Caveat Loan Work in Australia?
The process is built around speed and most applications move through five broad steps.
- The borrower identifies a property with sufficient equity to use as security. This can be residential, commercial or industrial property, and it may already carry a first mortgage provided there is enough equity remaining.
- The lender values the property and works out how much equity is available. Trading history carries far less weight than it would with a bank, and many caveat lenders do not look at credit files at all because the outcome turns on the security and the exit strategy.
- Once the loan is approved the lender lodges a caveat on the title, which records their interest and means the property cannot be sold or borrowed against further without the lender knowing about it.
- The funds are then released for a short, agreed term, which in most cases runs for weeks or a few months and not years.
- The loan is repaid, often through a refinance, a property sale or incoming cash flow, and the caveat is then removed from the title.
On eligible fast-finance products such as caveat loans, approval can be as fast as 24 to 48 hours, which is the standard turnaround Dark Horse works to for straightforward applications. Settlement is a separate step from approval and can follow in as little as 72 hours after approval, although this varies by lender and by how quickly documents are signed and returned, so it is sensible to allow some flexibility rather than plan around a single date.
Before any funds are released the borrower signs the loan and caveat documents, and having a solicitor review those documents first is strongly recommended.
Caveat Loan vs Second Mortgage vs Bank Loan: What's the Difference?
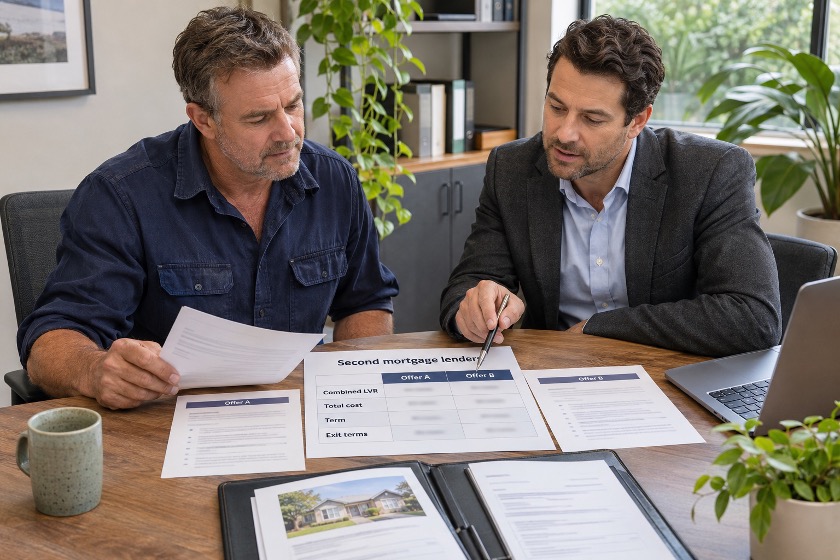
All three options can be secured against property, but they differ in how quickly they can be arranged, what form of security the lender takes and the situations they are designed for. The table below sets out the main differences.
| Caveat Loan | Second Mortgage | Traditional Bank Loan | |
|---|---|---|---|
| Speed to fund | Approval as fast as 24 to 48 hours on eligible products, with settlement possible in as little as 72 hours after approval, varying by lender | Slower, as it requires formal mortgage registration | Slowest, with a full credit assessment and settlement process |
| Security required | Caveat lodged on the property title (unregistered interest) | Registered second-ranking mortgage on the property | Registered first-ranking mortgage, often with other security as well |
| Typical use case | Short-term bridging, urgent cash flow needs and time-sensitive opportunities | Medium-term borrowing against existing equity, sitting behind an existing first mortgage | Longer-term business or property finance |
| Cost/rate profile | Generally higher interest rates and fees, reflecting the speed and short term; often quoted as a monthly rate | Typically sits between a caveat loan and a bank loan, varying by lender and term | Usually the lowest pricing of the three, but with the strictest approval criteria and longest timeframe |
The right choice depends on the borrower’s timeframe, their existing mortgage position and how quickly the funds are needed, rather than on price alone. A caveat loan suits a short, clearly defined funding gap where speed matters most, while a second mortgage or a bank loan is generally better suited to larger or longer-term needs where there is time to complete a fuller process. For a more detailed comparison, read our guide on the difference between a caveat loan and a second mortgage.

What Can a Caveat Loan Be Used For?
Caveat loans are versatile because they are secured by property equity rather than tied to a specific purchase, so the funds can be applied to a wide range of legitimate business purposes. Common uses include:
- Bridging finance while waiting on the sale or refinance of another property
- Covering a shortfall at settlement on a property purchase
- Urgent working capital for a time-sensitive business expense or opportunity
- Paying out a tax debt or ATO liability before it escalates
- Avoiding a forced or discounted sale of an asset by bridging a short-term cash gap
In each case the common thread is a need that is urgent, short-term and backed by a clear way to repay, which is exactly the situation the product was designed for.
Who Is Eligible for a Caveat Loan in Australia?
Eligibility centres on the equity available in the property being offered as security, rather than on an extensive financial history, and this is why caveat loans can suit businesses that might not qualify for traditional finance within the same timeframe. Many lenders in this space do not review credit files or credit history at all, which makes a caveat loan a realistic option for borrowers whose credit is impaired, provided the security is strong and the exit strategy is clear.
Caveat loans arranged through Dark Horse are for business purposes, and applications are generally made through a company or trust rather than by an individual. A long trading history is not required. Before applying, a business should have the following ready:
- A property with sufficient unencumbered or under-leveraged equity to offer as security
- A clear, short-term repayment plan, such as an expected sale, refinance or incoming cash flow event
- An understanding that the property’s title will carry a caveat for the term of the loan
A broker with access to a large panel of lenders can help confirm whether a specific property and situation qualifies, and match the application to the lender whose policy fits it best. You can learn more about how this works with Dark Horse’s caveat loans in Australia.
What If a Caveat Loan Isn't the Right Fit?
A caveat loan will not suit every situation. A business that does not hold suitable property equity, or one that needs funding over several years rather than a short-term bridge, is likely to be better served by a different structure, and taking on a short-term facility without a reliable exit can create more pressure than it relieves.
That does not mean the business is left without options. Dark Horse arranges finance across a wide range of products through a large panel of bank, non-bank and private lenders, including unsecured business loans, lines of credit, asset finance and longer-term secured lending. If a caveat loan is not the answer, it is worth exploring the full range of business loan options to find the structure that matches the purpose of the funds and the way the business will repay them.

Conclusion & Next Steps
A caveat loan is a fast, equity-secured way for a business to access short-term funds without going through a full mortgage process, and it works best when the need is urgent and the path to repayment is clear. Whether a caveat loan is the right fit, or another product from a large panel of lenders would serve the business better, depends on the property, the timeframe and the exit strategy.
If you would like to talk through your situation and understand which option suits it, speak to the team at Dark Horse Financial.
FAQs
A caveat loan is short-term finance secured by a caveat lodged on a property’s title, rather than by a registered mortgage. The caveat gives the lender a recorded interest in the property until the loan is repaid, and the product is typically used when a business needs funds quickly for a time-critical purpose.
Approval on eligible fast-finance products such as caveat loans can be as fast as 24 to 48 hours. Settlement is a separate step and can follow in as little as 72 hours after approval, but this varies by lender and by how promptly the borrower provides property details and signs the loan documents.
No, a caveat loan and a second mortgage are different products, because a caveat is an unregistered interest on title while a second mortgage is a registered one. As the comparison table above shows, this difference generally makes a caveat loan quicker to arrange but shorter in term, with a different cost profile.
Once the loan is repaid in full, the caveat is removed from the property’s title. The lender lodges a withdrawal of caveat with the relevant state or territory titles office, and the title then returns to its previous position, with any existing first mortgage unaffected by the process.
Eligibility depends primarily on the equity available in the property offered as security, together with a clear plan to repay the loan. As outlined in the eligibility section above, many lenders do not review credit history, and applications are generally made by a company or trust for a genuine business purpose.
Disclaimer: This article is general information only and does not take into account your objectives, financial situation or needs. It is not legal, tax or financial advice. Lender criteria, timeframes and costs vary and are subject to change. We recommend seeking independent legal advice before lodging or accepting a caveat over your property. Dark Horse Financial Pty Ltd is a Credit Representative No. 465 325 of Buyers Choice Licencing Pty Ltd.