No. Since 1 July 2025, the General Interest Charge (GIC) and Shortfall Interest Charge (SIC) incurred on ATO debts are no longer tax-deductible, and it makes no difference which income year the underlying debt relates to. Interest that was incurred before 1 July 2025 can still be claimed under the old rules. Source: ATO, “General interest charge” and “Denying deductions for ATO interest charges”, ato.gov.au, accessed September 2026.
Introduction
If you’ve been asking whether ATO interest is tax deductible, the short answer above covers it, but the detail underneath is where most of the confusion sits. The rule doesn’t care what year your tax debt comes from. It cares about the date the interest itself was charged, so a debt from 2019 that is still sitting on your account today is now accruing interest you can’t claim, right alongside the debt you missed last quarter.
That interest isn’t cheap either. For the October to December 2026 quarter the GIC rate is 11.51% per annum and the SIC rate is 7.51% per annum, both compounding daily, which is a fair step up from the 11.17% figure that was still floating around a lot of older articles (including an earlier version of this one).
This page pulls the questions we get asked most often about the ATO interest change of 1 July 2025 into a single dated, sourced reference. Where the answer turns into “so what do I actually do about it”, that’s the practical side of what Dark Horse Financial does every week in ATO tax debt resolution, and we’ve pointed you to the right places along the way.
Key Takeaways
- GIC and SIC incurred on or after 1 July 2025 are not tax-deductible for any taxpayer.
- Interest incurred before 1 July 2025 remains deductible under the previous rules, even if it’s claimed in a return lodged later.
- Current rates for the October to December 2026 quarter are GIC 11.51% p.a. and SIC 7.51% p.a., both compounding daily.
- The rule turns on when the interest is incurred, not which income year the original debt relates to. Old debt is not protected
- One published exception exists: entities on a substituted accounting period (a Commissioner-approved non-standard year-end, mostly companies) move to the new rule from their next accounting period starting after 1 July 2025, rather than the standard 30 June cutover.
- If interest you validly deducted is later remitted by the ATO, the remitted amount goes back into your assessable income in the year the remission is granted.
What Is ATO Interest, and Why Does the Deductibility Change Matter?
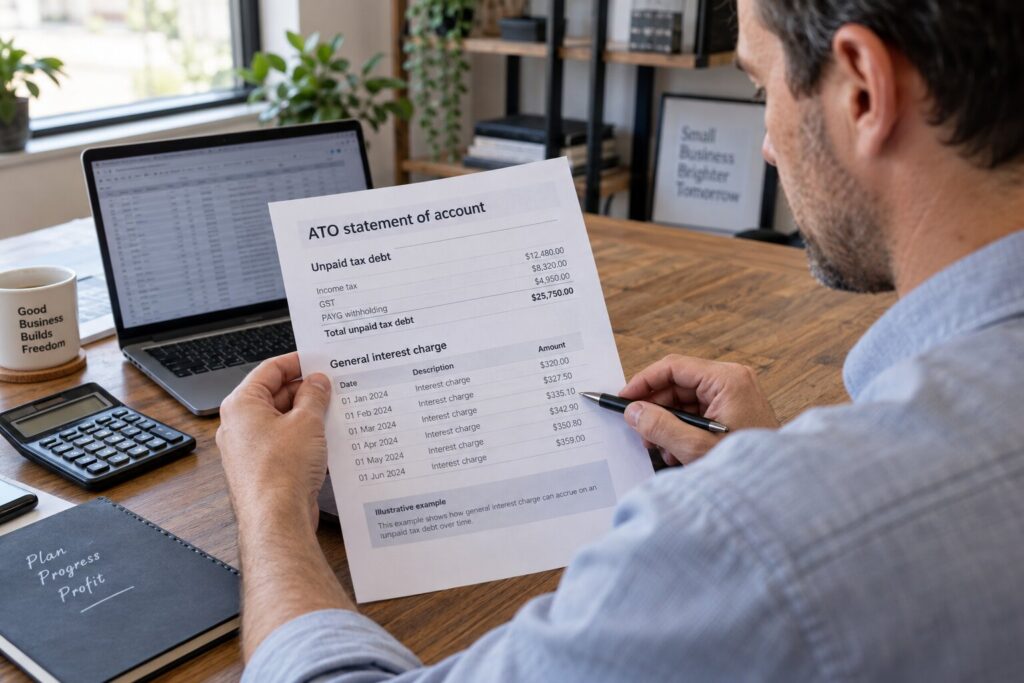
The ATO charges interest in two main ways, and although people lump them together as “ATO interest”, they’re triggered by different things. Understanding which one you’re paying matters, because both are now non-deductible and both compound every single day the balance sits there.
Before 1 July 2025, a business charged GIC or SIC could at least offset it against taxable income, which softened the blow. For a company paying tax at 25%, roughly a quarter of the interest effectively came back as a reduced tax bill. That cushion is gone. The full sticker rate is now the real after-tax cost of carrying ATO debt, and that’s the whole reason the question “is GIC tax deductible” has become so much more expensive to get wrong.
General Interest Charge (GIC)
GIC is the ATO’s broad-brush interest charge. It applies to almost any tax debt that isn’t paid by the due date: income tax, PAYG instalments, PAYG withholding, GST, FBT and more. It’s set quarterly, compounds daily, and keeps running until the balance is cleared or the ATO agrees to remit it. If you’ve got an overdue balance with the ATO right now, it’s almost certainly accruing GIC.
Shortfall Interest Charge (SIC)
SIC is narrower. It applies when the ATO amends an assessment and the amendment shows you should have paid more tax than you originally did. SIC covers the gap between the original due date and the amended assessment, at a lower rate than GIC, and once the amended amount falls due unpaid, GIC takes over. The full mechanics, including how the daily rate is applied, are covered in our shortfall interest charge (SIC) calculation guide.
The Rule Change in Detail: What the ATO Actually Announced
The change was legislated through the Treasury Laws Amendment (Tax Incentives and Integrity) Act 2025, and the ATO’s plain-English position is this: GIC and SIC incurred on or after 1 July 2025 can’t be claimed as a deduction in your income tax return. It doesn’t matter whether the debt arose in the 2019, 2022 or 2025 income year, and it doesn’t matter whether the debt came from a late BAS, an amended assessment or an old audit outcome. Source: ATO, “Denying deductions for ATO interest charges”, ato.gov.au.
The trigger is the date the interest is incurred. Not the date the debt was created, not the date you lodge, and not the date you eventually pay. A single ATO account can therefore hold two very different kinds of interest side by side: the pre-1 July 2025 portion, which you can still deduct in the year it was incurred, and everything charged from that date onward, which you can’t.
There is one exception the ATO has published, and only one. Entities with a substituted accounting period, meaning a Commissioner-approved year-end that isn’t 30 June (most commonly companies aligned to an overseas parent), lose the deduction from their next accounting period starting after 1 July 2025, not from 1 July itself. For a company with a 31 December year-end, for example, the rule takes effect from 1 January 2026. Source: ATO, “Denying deductions for ATO interest charges”, ato.gov.au.
If you come across any other claimed carve-out, whether it’s for small business, for hardship cases or for particular entity types, treat it with suspicion. Nothing of that kind appears in the ATO’s published guidance as at September 2026. Get it confirmed by a registered tax agent before you rely on it.
Current ATO Interest Rates, and Why They Compound Daily
For the quarter running 1 October to 31 December 2026, the ATO’s published rates are GIC 11.51% p.a. and SIC 7.51% p.a. Both are recalculated each quarter off the 90-day Bank Accepted Bill rate plus a fixed uplift (7 percentage points for GIC, 3 for SIC), and both compound daily. That last part is what people underestimate. Daily compounding means today’s interest is added to the balance tonight, and tomorrow’s interest is calculated on the slightly larger figure, every day, for as long as the debt is outstanding.
Put the two changes together and the picture is stark. The headline rate has climbed, and the deduction that used to claw back part of it has disappeared. A $150,000 GIC-bearing debt at 11.51% is costing something in the order of $47 a day before compounding, and none of that is now offsetting anything on your tax return.
| Charge | Rate (Oct to Dec 2026) | Compounding | Deductible? |
|---|---|---|---|
| General Interest Charge (GIC) | 11.51% p.a. (daily rate 0.03153425%) | Daily | No, for interest incurred on or after 1 July 2025 |
| Shortfall Interest Charge (SIC) | 7.51% p.a. (daily rate 0.02057534%) | Daily | No, for interest incurred on or after 1 July 2025 |
Source: ATO, “General interest charge rates” and “Shortfall interest charge rates”, ato.gov.au. Rates are reviewed quarterly. Confirm the current quarter’s rate at ato.gov.au before relying on these figures.

The Nuance Most Taxpayers Miss: Old Debt, New Non-Deductible Interest
This is the part of the change that receives the least attention. Because the ATO interest deductibility rules for 2026 hinge on when the interest is incurred rather than which year the debt belongs to, a tax debt from 2019, 2021 or any earlier year is now generating non-deductible interest, even though every cent of the original debt predates the rule change by years.
Think of it as two separate clocks. The first, attached to the principal, stopped when the debt was assessed, and nothing about the 2025 change touches the treatment of that principal. The second, the interest clock, has been running the whole time, and on 1 July 2025 the rules governing it changed for everyone at once. So the age of your debt gives you no protection at all. If anything, older debts are the more dangerous ones, because they’ve had longer to compound and they tend to be the ones people have quietly made peace with carrying.
It’s worth being precise about what is and isn’t affected. Only the interest has lost its deductibility. The underlying tax, whether it’s income tax, GST or PAYG withholding, was never deductible in the first place, so nothing has changed there. What has changed is that the running cost of leaving that debt unpaid is now borne entirely after tax.
The obvious next question is whether it’s smarter to pay the debt down from cash flow, negotiate a payment plan with the ATO, or refinance it through a lender whose interest may be deductible as a business expense. That’s a real decision with real trade-offs, and we’ve deliberately kept it off this page so we could do it justice elsewhere. If that’s where you’re at, compare a tax debt loan against ATO interest and payment plans in our dedicated guide.
Does This Apply to My Business Structure?
Yes, across the board. The change works by altering what counts as deductible interest under the income tax law, rather than by singling out a category of taxpayer, so it lands on sole traders, companies, trusts and partnerships alike. It applies to individuals with a personal tax debt just the same. If you incur GIC or SIC on or after 1 July 2025, you can’t deduct it, whatever your structure looks like.
Where structure does matter is in how the lost deduction actually flows through. A company paying tax at the 25% base rate loses a deduction worth 25 cents in the dollar. A sole trader or a trust distributing to beneficiaries on the top marginal rate loses closer to 47 cents in the dollar, so the after-tax pain is heavier the higher the marginal rate of whoever was ultimately claiming it. That’s not a loophole, just arithmetic, but it does mean two businesses with identical ATO debts can feel this change quite differently.
Companies on a substituted accounting period should also check their own transition date, as covered above.
None of this replaces personalised advice. This page explains the rule. Your registered tax agent is the one who can tell you how it interacts with your structure, your losses and your lodgement history.
How to Prepare for Non-Deductible ATO Interest
The first job is to get an accurate read on what you actually owe, because plenty of business owners are working off a number that is months out of date. Log into ATO Online Services or ask your registered tax agent or BAS agent to pull the current statement of account, and make sure it shows the daily interest accrual, not just the headline balance. With GIC compounding daily at 11.51%, the figure you saw at the end of last quarter is already wrong.
Next, model the real after-tax cost of carrying the debt. Before 1 July 2025 you could shave a chunk off the effective rate by claiming the interest. Now the effective rate is the full published rate, so a $200,000 debt at 11.51% is costing roughly $23,020 a year before compounding, with nothing coming back at tax time. Seeing that number in black and white tends to reframe the decision quite quickly.
Third, rank your debts. If you have several obligations on the go, the ones currently accruing GIC or SIC at these rates should generally sit at the top of the pile, ahead of older, lower-interest debts that are at least generating a deductible expense. It’s very common to see businesses diligently servicing a 7% equipment loan while an ATO balance compounds at 11.51% in the background.
Finally, weigh up your two main routes: an ATO payment plan, or clearing the balance with external finance. A payment plan keeps you inside the ATO system but the interest keeps ticking, and stays non-deductible, for the life of the arrangement. External finance stops the ATO interest clock and replaces it with a repayment you can budget for. The detailed comparison lives on our dedicated comparison page rather than here.
Can a Tax Debt Loan Help Manage ATO Interest Charges?
In the right circumstances, yes. A tax debt loan clears the ATO balance outright, which stops GIC or SIC accruing from the day the payment lands. In its place you take on a structured repayment with a lender, at a rate and over a term you’ve agreed up front, so the open-ended, daily-compounding, non-deductible cost is swapped for a fixed and predictable one. For many businesses, that predictability alone is worth a great deal, quite apart from any rate comparison.
Clearing the ATO debt also brings your account back into good standing, which matters when you next need finance or when the ATO is beginning to escalate its recovery activity, and it removes the risk of a payment plan defaulting and the whole balance falling due at once.
Dark Horse Financial works with a panel of more than 100 lenders, spanning the major banks, non-bank lenders and private financiers. That breadth matters with tax debt, because a fair number of mainstream lenders still treat an ATO balance as a red flag rather than a problem to be solved, so knowing which lenders will look at a tax debt scenario, and on what terms, is most of the battle. On some unsecured products, approval can be as fast as 24 to 48 hours. That isn’t every product and it isn’t every borrower, but for a business watching interest compound daily, speed is often the difference between a manageable outcome and an expensive one.
We won’t claim to have the cheapest option, because nobody honestly can before they’ve seen your situation. What we can do is assess your position against the lenders who are actually active in this space and put forward something competitive that fits how your business runs.
Where This Fits: Understanding the Full ATO Interest Cluster
We’ve written three pages on ATO interest, and each one has a distinct job, so it’s worth being clear about which is which before you go clicking around.
This page is the FAQ and reference hub. It answers the “what changed, when did it change and does it apply to me” questions about ATO interest no longer being deductible, and it’s the page we’ll keep updated as rates move each quarter.
Our shortfall interest charge (SIC) calculation guide is the how-to-calculate page. It owns the SIC formula, the daily rate mechanics and the worked examples, so if you’ve received an amended assessment and want to understand the number on it, start there.
The comparison page is the how-to-decide page. It sets a tax debt loan against ATO interest and ATO payment plans side by side, and works through when each option is likely to come out ahead. Our main tax debt loans page then covers the finance itself: what’s available, who it suits and how the process runs.
FAQs About ATO Interest No Longer Being Deductible
No. As of 1 July 2025, GIC and SIC incurred on or after that date are not tax-deductible for individuals or businesses, according to current ATO guidance. This applies regardless of the type of tax debt or the year it relates to. Interest incurred before 1 July 2025 remains deductible. Source: ATO, “Denying deductions for ATO interest charges”, ato.gov.au.
ATO interest stopped being deductible for interest incurred from 1 July 2025 onward. Any GIC or SIC charged before that date remains deductible under the previous rules, in the income year in which it was incurred. The dividing line is the date the interest was charged, not the date your debt arose or the date you lodge your return.
The stated intent was to remove the advantage that taxpayers who delayed paying the ATO enjoyed over those who paid on time or borrowed commercially to do so. Allowing GIC and SIC to be deducted effectively made ATO debt a cheap, tax-effective form of finance, and the government legislated to close that off.
Yes. GIC and SIC incurred before 1 July 2025 remain deductible, even if you claim them in a return lodged after that date, because deductibility turns on when the interest was incurred rather than when it’s claimed. Keep in mind that if the ATO later remits that interest, the remitted amount must be included as assessable income in the year the remission is granted. Source: ATO, “General interest charge”, ato.gov.au.
No. The rule depends solely on when the interest itself was incurred, not on which income year the underlying tax debt relates to. A debt from 2019 or 2021 that is still unpaid is now accruing non-deductible GIC in exactly the same way as a debt from last quarter. The age of the debt provides no protection from the new rule.
Start by getting a current statement of account from the ATO or your registered tax agent, including the daily interest accrual. Then model the real after-tax cost of leaving the debt unpaid at the full published rate, since none of it can now be claimed. Finally, compare an ATO payment plan against external finance options such as a tax debt loan, and prioritise the debts accruing GIC or SIC.
Only the portion of GIC or SIC incurred before 1 July 2025 is claimable. If your return covers a period spanning that date, it may contain both deductible and non-deductible interest, and the split depends entirely on the dates each amount was incurred. Your ATO statement of account shows the daily interest postings, which is what your tax agent will use to separate the two.
One published exception exists. Entities on a substituted accounting period, meaning a Commissioner-approved non-standard year-end (mostly companies), lose the deduction from their next accounting period starting after 1 July 2025 rather than from 1 July itself. Source: ATO, “Denying deductions for ATO interest charges”, ato.gov.au. No other exception appears in ATO guidance, and a registered tax agent should confirm whether any rule applies to your specific situation.
Yes. Where GIC or SIC was validly deducted for the 2024-25 or an earlier income year and the ATO later remits it, the remitted amount must be included in your assessable income in the year the remission occurs. Source: ATO, “Denying deductions for ATO interest charges”, ato.gov.au. Remitted interest incurred from 1 July 2025 has no such consequence, because it was never deducted
Conclusion: The Interest Clock Is Running, Whatever Your Plan
GIC and SIC haven’t been deductible since 1 July 2025, they compound daily at rates that have climbed through 2026, and the date the interest is incurred, not the year your debt was born, is the only thing that determines the treatment. The single published exception is the substituted accounting period timing rule for entities with a non-standard year-end. Everyone else is on the same footing.
This page is general information only and is not personal tax advice. Speak with a registered tax agent about how the rule applies to your specific situation before making decisions.
If you’re carrying ATO debt and want to know what your options are for stopping the interest clock, speak with our team about your ATO debt. We’ll assess your position against our panel of 100+ lenders, usually the same day, and tell you plainly what’s realistic.
Sources and Methodology
Australian Taxation Office, “Denying deductions for ATO interest charges”, ato.gov.au/about-ato/new-legislation/in-detail/businesses/deny-deductions-for-ato-interest-charges, accessed 13 September 2026.
Australian Taxation Office, “General interest charge”, ato.gov.au/individuals-and-families/paying-the-ato/interest-and-penalties/interest-we-charge/general-interest-charge, accessed 13 September 2026.
Australian Taxation Office, “General interest charge rates”, ato.gov.au/tax-rates-and-codes/general-interest-charge-rates, accessed 13 September 2026.
Australian Taxation Office, “Shortfall interest charge rates”, ato.gov.au/tax-rates-and-codes/shortfall-interest-charge-rates, accessed 13 September 2026.
Treasury Laws Amendment (Tax Incentives and Integrity) Act 2025 (Cth).
Methodology: Rates quoted are the ATO’s published figures for the 1 October to 31 December 2026 quarter and were checked directly against ato.gov.au on the access date above. Worked dollar figures are simple annualised illustrations that exclude daily compounding and are provided for scale only. Page last reviewed 13 September 2026.
Disclaimer
The information provided on this page is general in nature and does not constitute financial, taxation, or legal advice. It does not take into account your personal circumstances, objectives, or needs and should not be relied upon for any reason. Before making any decisions, you should seek independent professional advice tailored to your specific situation.
Disclaimer: Loans and the benefits associated with them are only available to those who have been approved.
Clear Your Tax Debts In Time
For tailored advice on tax debt loans, refinancing, or debt consolidation solutions, contact Dark Horse Financial today. We specialise in helping Australian businesses manage their tax obligations and access funding when they need it most.
Disclaimer: The information provided on this page is general in nature and does not constitute financial, taxation, or legal advice. It does not take into account your personal circumstances, objectives, or needs and should not be relied upon for any reason. Before making any decisions, you should seek independent professional advice tailored to your specific situation.